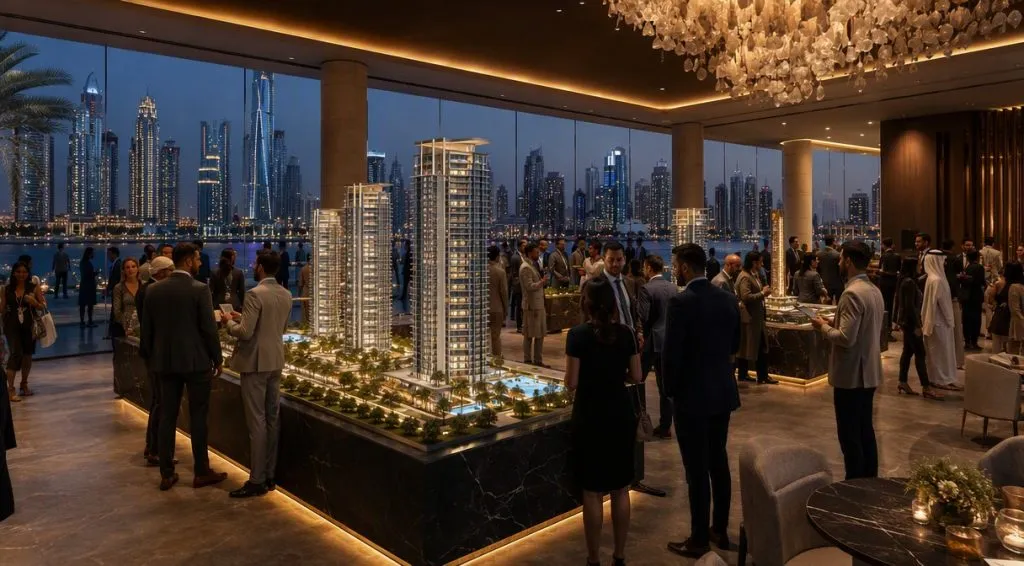
Days ago, the UAE was ranked first among nine emerging family office hubs worldwide, scoring 74 out of 100 and outscoring the United States, the United Kingdom, Liechtenstein and Monaco in Global Citizen Solutions' study of 33 jurisdictions. Dubai is where much of that verdict becomes visible on the ground.
The Dubai International Financial Centre recorded 1,408 family business-related entities by the end of June 2026, growth of 36 per cent year on year, and the city now ranks seventh among the world's financial centres in the 2026 Z/Yen classification. The capital these structures manage is flowing directly into the emirate's property market, and the developers capturing it are running at record pace.
Why family offices anchor in Dubai
DIFC introduced its family office regulatory framework in 2008, giving the centre nearly two decades of accumulated ecosystem: common law courts, the Family Arrangements Regulations, and a deep bench of trustees, private banks and legal counsel. Around it, the UAE offers zero personal income tax and a statutory zero rate on wealth passing to the next generation.
This is precisely what the Global Citizen Solutions report describes: terms open the door, but the ecosystem keeps it open. The UBS Global Family Office Report 2026 found that 88 per cent of family offices now hold bankable assets in two or more jurisdictions, and Deloitte projects family office wealth will grow from US$5.5 trillion in 2024 to US$9.5 trillion by 2030, with single family offices rising from 8,030 to 10,720. Dubai is capturing a disproportionate share of that formation.
Investor Proof
The Abu Dhabi Off-Plan Flip Strategy, Proof of Concept
Three executed transactions, real contracts, and a blended 62% ROI in 12 months with only 20% capital deployed before resale.
- ≈62% blended ROI, 12-month cycle
- 20% capital deployed pre-resale
- AED 3.4M profit locked across 3 flips
Download the Proof of Concept
Instant download once the required fields are complete.
Thank you.
The market they are buying into
Off-plan transactions made up 66 per cent of all Dubai property sales in the first half of 2026, and the UAE's top ten developers sold AED 113.7 billion of real estate between January and June alone. For institutional-scale family capital, that depth matters: it means liquidity on entry, an active resale market on exit, and a developer bench with funded construction pipelines rather than speculative promises.
The developers setting the pace
DAMAC Properties leads Dubai's 2026 league table by sales value with AED 16.77 billion year to date, and closed 2025 with AED 36 billion as the country's largest private developer. Its branded residence strategy, from Cavalli and Versace to Bugatti, has defined the segment, and DAMAC Islands 2 famously sold AED 11 billion within five hours of launch in November 2025.
Free Investor Guide
The Abu Dhabi Investment Guide
District-by-district yields, payment-plan mechanics, service charges and exit liquidity, everything we brief our private clients on, in one guide.
Get the Guide
We will send it straight to you.
Thank you.
The guide is on its way to your inbox. Our team may follow up once, no spam, ever.
Emaar Properties follows with AED 16.01 billion year to date and remains the market's anchor: AED 22.4 billion of property sales in H1 2026, a revenue backlog of AED 164.9 billion, more than 84,000 homes delivered since 2002 and 51,000 under development across Dubai Hills Estate, Dubai Creek Harbour, Rashid Yachts and Marina and The Oasis.
Binghatti holds third at AED 9.64 billion, built on its branded tower strategy with Mercedes-Benz, Bugatti and Jacob and Co, a portfolio above 100 projects and an H1 2026 development backlog of AED 44.2 billion. Azizi Developments leads by transaction count with 11,437 sales year to date, dominating the accessible investor segment around MBR City and Al Furjan.
Sobha Group remains the quality benchmark, with a fully integrated in-house model, FY 2025 sales of AED 30 billion and 6,819 handovers planned in Dubai for 2026. At the ultra-prime end, Nakheel (Palm Jebel Ali, where villas start near AED 18.5 million, and Dubai Islands), Meraas and Omniyat (The Lana, ORLA, One Palm) supply the trophy inventory family offices favour, while Ellington leads the boutique design-led tier at AED 8.24 billion year to date.
What family capital actually buys in Dubai
The pattern we observe is consistent: branded residences for yield and global recognisability, waterfront villas on Palm Jebel Ali and Jumeirah Bay for preservation, and prime towers in Downtown and Business Bay for liquidity. Average ticket sizes tell the story: Nakheel trades near AED 5.4 million per transaction, Emaar near AED 3.5 million, while volume players average under AED 1 million.
Dubai's proposition to a family office is no longer speculative yield. It is a regulated, escrow-protected off-plan framework, deep resale liquidity and a financial centre that can hold the structure, the family and the assets in one jurisdiction.
Our view
Dubai offers scale and velocity unmatched in the region. For families allocating fresh capital, we advise pairing Dubai's liquidity with Abu Dhabi's scarcity: the two markets now move on the same capital flows but price risk very differently. Our advisory team structures cross-emirate portfolios for private clients every week, and the balance between the two is where the real value sits in 2026.
Discuss Your Investment Strategy
Read something that fits your plans? Speak with our advisory team.
Thank you.
Thank you, our team will be in touch shortly.
Keep Reading
Related Insights
Market News & Analysis
Abu Dhabi vs Dubai for Off-Plan Investment (2026)
Written by the Bramwell & Partners advisory team, Abu Dhabi real estate advisors. Last reviewed: October 2026. Every week, buyers ask us some version of…
Market News & Analysis
Nawayef East Hills by Modon: Prices & Investment Case
Written by the Bramwell & Partners advisory team, Abu Dhabi real estate advisors. Last reviewed: October 2026. Nawayef East Hills is Modon's ultra-prime…
Market News & Analysis
Modon & ADIB 75% Off-Plan Financing Explained
Written by the Bramwell & Partners advisory team, Abu Dhabi real estate advisors. Last reviewed: October 2026. On 7 July 2026, Modon Holding and Abu…