Written by the Bramwell & Partners advisory team — Abu Dhabi real estate advisors. Last reviewed: October 2026.
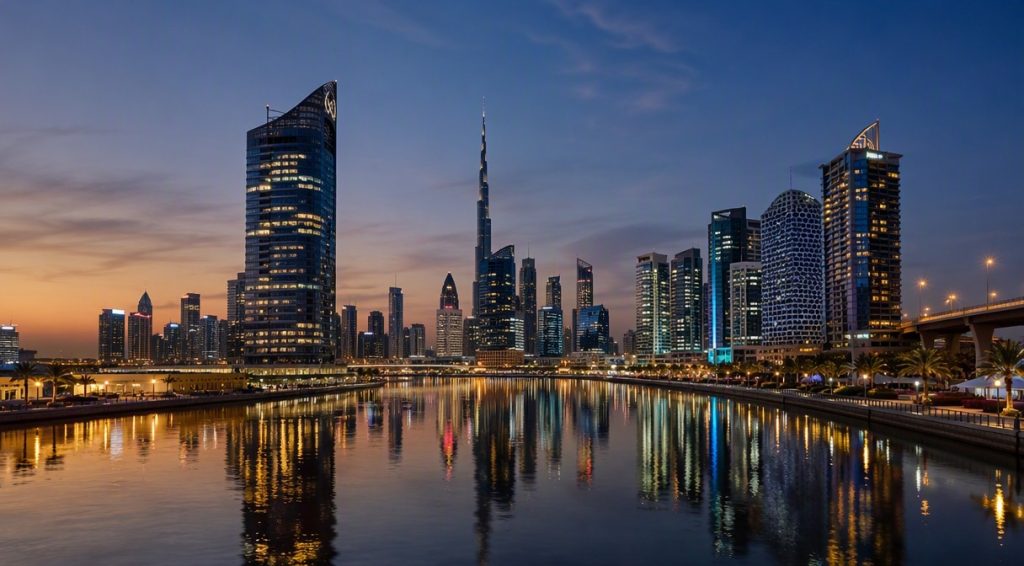
Business Bay is Dubai’s central high-rise district: a canal-led grid of towers directly south of Downtown, between DIFC, Sheikh Zayed Road and Al Khail Road. For off-plan buyers it offers something few districts can — a near-prime postcode with genuine apartment choice, from compact investor units to branded residences such as Bugatti Residences and canal-front towers by Omniyat, Ellington, Binghatti, Deyaar and Al Habtoor. Indicative entry prices for mainstream new launches start around AED 1.2–1.5 million, while the branded tier runs from AED 5 million to well above AED 19 million.
The district’s challenge is also its appeal: density. Two towers a street apart can trade at very different prices and rents. This guide gives you the numbers to compare them properly — prices, rents, yields and the service charges that decide your net return.
Key takeaways
- Business Bay is an apartment-led, centrally located market where tower position — canal frontage, view corridor, brand, floor — drives price more than the district name.
- Market data puts average one-bedroom asking prices around AED 1.6 million and rents near AED 100,000–105,000 a year, implying gross yields of roughly 6–6.5% — strong for a central postcode.
- Service charges are the swing factor: approximately AED 15–25 per sq ft per year is typical for newer full-amenity towers, and branded buildings run higher.
- Heavy concurrent supply is the main risk; Business Bay is among the Dubai districts with the largest upcoming inventory, so unit selection and pricing discipline matter.
- Best fit: investors wanting tenant depth and liquidity, and end-users working in DIFC, Downtown or the canal corridor.
Business Bay is one of Dubai’s most liquid apartment markets. Based on H1 2026 market-report data (Bayut’s analysis of listing and DLD figures), a typical one-bedroom apartment asked around AED 1.6 million and rented for roughly AED 104,000 a year — a gross yield near 6.4%. Studios and compact one-bedrooms in well-managed secondary towers can push towards 7% gross; large branded units yield less because capital values outrun rents.
Those are market-level figures, and Business Bay rewards street-level precision. Canal-front towers with Burj Khalifa sightlines transact at a visible premium to back-row buildings; units facing Sheikh Zayed Road trade at a discount that some investors deliberately buy for yield. The same logic applies at resale: the audience for a canal-view two-bedroom is deeper than for an internal-view studio at the same per-square-foot price.
Walk the district with us at 6pm and the pattern is visible: the canal promenade fills with runners from the DIFC crowd, valet queues form at the canal-side hotels, and towers two streets back from the water sit noticeably quieter — and noticeably cheaper to rent. Traffic noise from Sheikh Zayed Road is real on north-facing lower floors; we check it from the exact stack height on site, not from the sales gallery.
The live pipeline spans a wide range of positioning. Indicative guide prices below reflect advertised starting levels in late 2026 and change by release — confirm in writing before reserving.
| Project (developer) | Product | Indicative entry | Positioning |
|---|---|---|---|
| DWTN Residences (Deyaar) | Apartments, duplexes, penthouses | ~AED 1.5–2m | Large-scale central tower, Q4 2029 target |
| Binghatti Skyrise / Skyhall (Binghatti) | Apartments | ~AED 1.2–1.8m | Volume investor product, phased handovers |
| One River Point (Ellington) | Apartments, duplexes | ~AED 2.3m+ | Design-led canal-side tower |
| Al Habtoor Tower (Al Habtoor) | Apartments | ~AED 2.5m+ | Amenity-heavy mega-tower on the canal |
| Avarra by Palace (Emaar) | Branded apartments, sky villas | ~AED 3m+ | Palace-branded, Q2 2031 target |
| Bugatti Residences (Binghatti) | Branded apartments & penthouses | ~AED 19m+ | Ultra-prime branded, canal frontage |
| Wedyan – The Canal (Al Ghurair) | Apartments, penthouses | By enquiry | Low-density canal-front boutique |
Payment plans across the district typically run 10–20% on booking, 40–60% during construction and the balance on handover, with several developers offering post-handover tails of 20–30% over two to three years. Post-handover plans ease the completion moment but do not reduce the price — model the full schedule, including the Dubai Land Department’s 4% registration fee, trustee and admin fees, and furnishing.
Business Bay’s gross yield of roughly 6–6.5% on mainstream apartments is attractive for a central district, but net is the number that pays you. Work through a typical one-bedroom:
Netted honestly, a well-bought mainstream Business Bay one-bedroom lands around 4.5–5.25% net — competitive against central London or Singapore, and thinner than JVC’s net profile. The offset is liquidity and tenant depth: corporate tenants, furnished-rental operators and end-user buyers give Business Bay one of Dubai’s broadest exit audiences.
Business Bay has quietly become a liveable district rather than a purely commercial one. The Dubai Canal promenade is the organising feature: a 3.2-kilometre waterfront loop used for running, cycling and evening walks, with the waterfall bridge at the Sheikh Zayed Road crossing. Bay Avenue provides everyday retail, supermarkets and casual dining, while the canal-side hotels — including the JW Marriott Marquis and the SLS — add destination restaurants and rooftop venues. Downtown Dubai’s full amenity set (Dubai Mall, the Opera district, the Burj Khalifa boulevard) is minutes away by car or a manageable walk from the canal’s north side.
Transport is a genuine strength: the Business Bay metro station on the Red Line serves the district’s north, and Sheikh Zayed Road, Al Khail Road and Al Asayel Street give drivers three exits. For tenants working in DIFC, the commute can be under ten minutes. Schools are the one thin spot — families typically look to Jumeirah, Al Safa or Nad Al Sheba — which is why the district’s buyer base skews towards professionals, couples and investors rather than households with school-age children.
Bramwell & Partners — Investor Proof
We help investors make money investing in Abu Dhabi properties — and we can prove it.
Download our Proof of Concept: three executed off-plan flips, real contracts, ≈62% blended ROI in 12 months with only 20% capital deployed.
Downtown is the fuller lifestyle address and carries the stronger brand premium; Business Bay is the pragmatic version of the same centrality, typically at a 15–30% per-square-foot discount to comparable Downtown towers. For end-users who value the walkable boulevard life, Downtown justifies its premium. For investors underwriting tenant demand from the DIFC corridor, Business Bay usually delivers the better yield-to-price equation — and it is where most of the current off-plan choice actually sits.
The central-corridor investor. You want DIFC/Downtown tenant demand, furnished-rental depth and resale liquidity, and you accept mid-5s net yields in exchange. Buy the best-managed building you can, not the cheapest unit.
The canal-and-view end-user. You work in DIFC, Downtown or along Sheikh Zayed Road and value a walkable canal lifestyle. Pay the view premium only after confirming which adjacent plots can still build — view corridors in Business Bay are not guaranteed.
The branded-residence buyer. Bugatti, Palace and similar towers suit buyers who will use the service and amenity load. Underwrite the higher service charge for the life of ownership, not just the launch price.
Who should pause: buyers who need maximum yield per dirham (JVC, Arjan or Dubai South will beat Business Bay on net income), and anyone stretching to a branded-tower price on the strength of the area name alone.
An illustrative brief we see often: a DIFC-based professional choosing between a canal-view one-bedroom at a premium and an internal-view two-bedroom for the same money. For own use, the view won; for pure yield, the larger internal unit rented faster and netted more. The right answer changes with the buyer — which is why we model both before anyone reserves.
Expert view from Bramwell & Partners
"Our advice in Business Bay is always tower-first, district-second. We pull the building’s approved service charge, check the developer’s delivered towers in comparable locations, map the plot against future construction, and model the net yield at a conservative rent. Two projects we reviewed for clients this year sat in the same price band; one netted a point and a half more purely on service charges and unit mix. In a district with this much supply arriving, that discipline is the whole game."
Before paying a booking amount on any Business Bay tower, run the standard Dubai checks with extra rigour, because density punishes sloppy selection. Confirm the project through the DLD’s Project Status Enquiry and pay only into the registered escrow account. Inspect at least one completed tower by the same developer — lobby condition, lifts, corridors and facilities management after a few years say more than any render. Check the exact plot on the masterplan for canal distance, road exposure and future construction that could take your view, and pull the building’s approved service charge where a sister building exists. Budget the 4% DLD registration fee, trustee fees, valuation and mortgage costs if financing, and furnishing. Business Bay is a designated freehold area, and units of AED 2 million or more can support a Golden Visa application subject to current rules.
Yes for buyers prioritising centrality, tenant depth and liquidity. Gross yields on mainstream apartments run roughly 6–6.5%, netting around 4.5–5.25% after service charges, vacancy and management. The main risk is concurrent supply — many similar towers complete in the same windows, so unit selection and entry price matter more than the district label.
Market data for H1 2026 puts average one-bedroom asking prices around AED 1.6 million, with two-bedrooms near AED 2.5–3 million and studios from roughly AED 1 million, varying sharply by tower position, view and brand. Branded and canal-front product sits far above the district average.
Newer full-amenity towers typically run AED 15–25 per sq ft per year; branded and hotel-serviced residences can exceed that materially. Every Dubai building’s approved charge is published on the DLD’s Mollak system — check the exact tower before reserving.
They solve different problems. JVC offers lower entry prices and higher gross yields (around 7%); Business Bay offers centrality, a corporate tenant pool and stronger liquidity. Yield-first budgets usually suit JVC; buyers wanting a central asset with resale depth lean to Business Bay.
Commonly 10–20% on booking, 40–60% during construction and the balance at handover, with some developers adding 20–30% post-handover over two to three years. Add the 4% DLD registration fee and furnishing to your cash-flow plan.
Yes. Business Bay is a designated freehold area, so non-UAE nationals own outright. Purchases of AED 2 million or more can also support a Golden Visa application, including qualifying off-plan units, subject to current rules.
How we verify this guide. Market figures draw on Bayut’s H1 2026 reports (based on DLD data) and DLD Mollak service-charge records; project prices are indicative advertised levels checked October 2026. Confirm live pricing, availability and the building’s approved service charge at enquiry.
Disclosure: Bramwell & Partners may act for buyers in some projects mentioned; our analysis is independent of developers.
Bramwell & Partners advises buyers across Dubai and Abu Dhabi. For Business Bay we will pull tower-level service charges, registered comparable transactions and live release pricing, and tell you which side of a view premium is worth paying.
Browse current off-plan projects · See Business Bay sales and rental listings · Enquire with Bramwell & Partners for a confidential consultation.
Institutional-Grade Investment Guidance
Talk directly to our advisory team
WhatsApp us at +971 56 494 7631 — we reply personally, usually within the hour.