Written by the Bramwell & Partners advisory team — Abu Dhabi real estate advisors. Last reviewed: October 2026.
Beyond Developments is the youngest brand in this developer series — launched in 2024, with its first building (Aria) handing over only in October 2027 — and the one with the most interesting parentage. Beyond is OMNIYAT Group’s accessible-luxury brand: the design language of The Opus and One at Palm Jumeirah, carried into towers priced from AED 1.6 million in Dubai Maritime City.
That combination — an unproven brand backed by a proven luxury developer — is exactly what buyers struggle to price. This review from Bramwell & Partners gives Beyond a transparent track-record score, explains precisely how much the OMNIYAT halo is worth, maps its 14 current projects, and sets out who should buy early and who should wait.
Key takeaways
- Beyond Developments launched in 2024 under OMNIYAT Group founder Mahdi Amjad; it is a brand of the group, not an independent developer.
- 14 current projects, nine in Dubai Maritime City, plus Palm Jumeirah, Dubai Islands, City of Arabia and Al Marjan (RAK); all handovers 2027–2029 — nothing completed yet.
- Entry prices: AED 1.0M (Arancia Yards, City of Arabia), AED 1.6M in Maritime City (Aria), AED 4.1M on Palm Jumeirah (Passo, Bella by Passo).
- Payment plans: mostly 10/40/50 — half the price due at handover.
- Our track-record score: 11/20 — strong parental backing and design pedigree, zero completed stock, unproven district. A calculated early-entry bet, not a safe harbour.
Beyond is a premium, design-led residential brand launched by OMNIYAT Group in 2024. Where OMNIYAT’s flagship line builds AED 30 million-plus statement addresses — The Opus by Zaha Hadid, One at Palm Jumeirah, ORLA — Beyond targets the AED 1–8 million "wider luxury" band: design-forward apartments, duplexes and townhouses with wellness-led amenities, at prices a broader buyer pool can reach.
The brand’s identity rests on three pillars: architecture-led design, wellness and nature-centric planning, and waterfront locations. Its centre of gravity is a new residential district in Dubai Maritime City on the Jumeirah coastline, developed in collaboration with the district’s master developer — nine of Beyond’s 14 current projects sit there.
This is the central question, and most profiles answer it with adjectives. Our framework: a parent group’s record transfers to a sub-brand in proportion to what is contractually and operationally shared — and buyers should discount everything else.
What transfers:
What does not transfer:
Our conclusion: the halo is worth roughly a one-to-two-point uplift on a young brand’s delivery-risk score — meaningful, but it does not convert an early-stage bet into a safe one.
The four pillars are weighted equally and scored on evidence, not reputation: delivery history counts completed, visitable handovers; build quality is judged on finished stock; payment-plan flexibility measures how instalment structures treat cash versus financed buyers; and resale performance reflects actual secondary-market depth. For a brand with no completions, the first two pillars are necessarily scored on parental evidence and marked provisional — the identical framework applied to every developer in this series, including the honest zeros. See our 2026 UAE developer ranking.
| Dimension | Score /5 | Justification |
|---|---|---|
| Delivery history | 2.0 | None yet — first handover (Aria) is October 2027. Parent-group record (OMNIYAT: The Opus, One at Palm Jumeirah, ORLA) earns the score above zero; the brand itself has delivered nothing. |
| Build quality | 2.5 | Unproven at handover. Design intent and specification are strong on paper and consistent with OMNIYAT’s culture, but no completed building exists to inspect. Provisional score. |
| Payment-plan flexibility | 3.5 | Simple, consistent menu: 10/40/50 on most projects, 10/50/40 on Palm Jumeirah, 10/30/60 on Arancia Yards. Low 10% entry; heavy 50% handover balances are the trade-off. |
| Resale performance | 3.0 | No resale market exists. Scored on the demand evidence available: rapid sell-through on early Maritime City phases and OMNIYAT flagships’ strong secondary performance suggest healthy launch-to-handover dynamics — but this is inference, not evidence. |
| Overall | 11.0 / 20 | An early-entry proposition: you accept delivery and market risk in exchange for pre-completion pricing in a district still being priced by the market. Size positions accordingly. |
Published starting prices; confirm live availability — phases sell through and reprice.
Dubai Maritime City (nine projects):
| Project | From price | Payment plan | Handover |
|---|---|---|---|
| Aria by Beyond | AED 1.6M | 10/40/50 | Oct 2027 |
| Orise by Beyond | AED 1.92M | 10/40/50 | Jan 2028 |
| Saria by Beyond | AED 2.0M | 10/40/50 | Oct 2028 |
| Sensia by Beyond | AED 2.1M | 10/40/50 | Oct 2028 |
| Talea by Beyond | AED 2.2M | 10/40/50 | Jan 2029 |
| Kanyon | AED 2.4M | 10/40/50 | May 2029 |
| The Mural by Beyond | AED 2.47M | 10/40/50 | Oct 2028 |
| Soulever Towers | AED 2.9M | 10/40/50 | Jan 2029 |
| 31 Above (offices) | AED 7.5M | 10/40/50 | Mar 2029 |
Outside Maritime City:
| Project | Location | From price | Payment plan | Handover |
|---|---|---|---|---|
| Arancia Yards | City of Arabia | AED 1.0M | 10/30/60 | Jan 2029 |
| Hado | Dubai Islands | AED 2.2M | 10/40/50 | Aug 2029 |
| Le Château | Al Marjan Beach District, RAK | AED 2.3M | 10/40/50 | Nov 2029 |
| Bella by Passo | Palm Jumeirah | AED 4.1M | 10/50/40 | Dec 2029 |
| Passo by Beyond | Palm Jumeirah | AED 4.1M | 10/50/40 | Dec 2029 |
Compare these against wider UAE launches in our off-plan portfolio.
Bramwell & Partners — Investor Proof
We help investors make money investing in Abu Dhabi properties — and we can prove it.
Download our Proof of Concept: three executed off-plan flips, real contracts, ≈62% blended ROI in 12 months with only 20% capital deployed.
The standard 10/40/50 plan, worked through on Aria at AED 1.6 million: AED 160,000 to book, ~AED 640,000 across construction, and AED 800,000 due at handover in October 2027. Two implications:
Add Dubai’s 4% DLD fee and Oqood registration. If your thesis is resale before handover, model a flat market: Maritime City premiums depend on the district maturing on schedule.
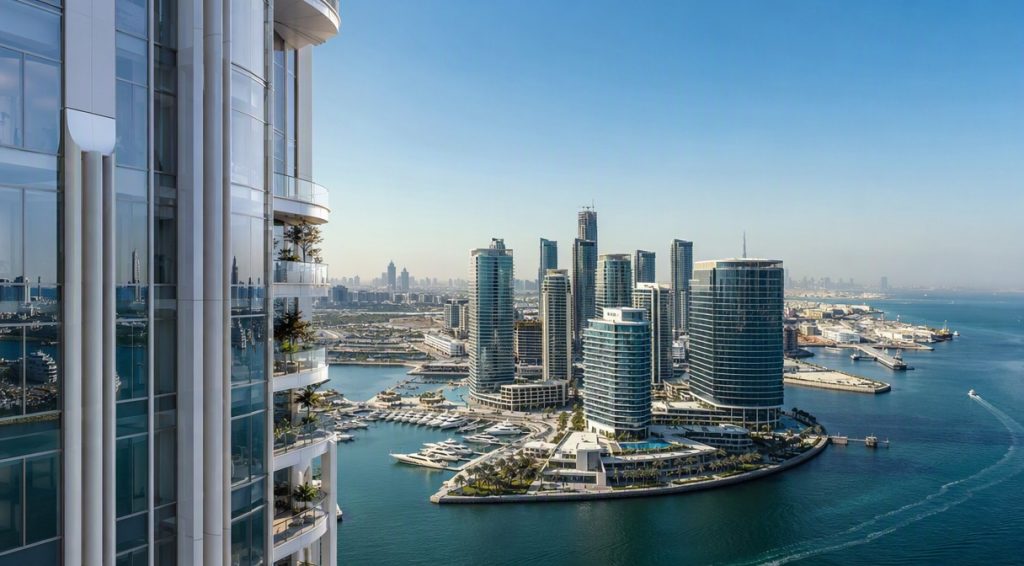
Nine of fourteen projects makes Beyond effectively a district bet. Dubai Maritime City is a peninsula between Port Rashid and the Jumeirah coastline — genuinely waterfront, minutes from DIFC and Downtown, and still early in its residential story. Entry prices (~AED 2,000–2,600 per sq ft on recent launches) sit below comparable waterfront districts like Emaar Beachfront or Dubai Creek Harbour’s prime stock, which is the opportunity; the surrounding infrastructure, retail and streetscape are years from maturity, which is the risk. Districts like this reward early buyers when the masterplan lands on time and punish them when it slips. Underwrite the timeline, not the render.
Buying a pre-handover brand is a different advisory conversation: there is no completed lobby to walk through, so we substitute what can be verified — the contractor on site, construction progress photographed month by month, and OMNIYAT’s completed buildings as a proxy for finish culture. When we negotiate Beyond allocations for clients, early-release units at Aria and Orise were meaningfully cheaper per square foot than later Maritime City releases — the price ladder rewards decisiveness, which is precisely why we insist clients complete their financing plan before launch day rather than after.
An illustrative scenario: a UK-based buyer wanted early Dubai Maritime City exposure with a AED 2 million cap. We compared Aria (2027 handover, 10/40/50) against a ready Business Bay apartment at similar money. The client chose Aria — accepting construction risk deliberately — but sized the position so the handover payment sits in cash, unborrowed. That sizing, not the project choice, is what makes the risk acceptable.
Expert view from Bramwell & Partners
Beyond is the kind of proposition we like for the right client: a short construction window, a credible parent, and district pricing that still has room to converge with established waterfront neighbours. Our advice is disciplined: buy the earliest handover you can (Aria, Orise) rather than the 2029 stock, cap exposure at a size you can complete without a mortgage, and treat any pre-handover premium as a bonus, not a plan. For buyers who simply want design-led Dubai waterfront with less execution risk, completed OMNIYAT or Ellington stock — or Abu Dhabi’s Saadiyat Island, where Aldar and completed Mamsha residences offer culture-district waterfront with a live resale market — may be the better trade. We model both paths for clients.
Beyond is a brand under OMNIYAT Group, launched in 2024 by founder Mahdi Amjad — not a separate developer and not the flagship line. OMNIYAT’s team and resources stand behind it operationally, but each Beyond project is its own legal purchase with its own escrow, SPA and handover date. Verify at project level.
No. All 14 current projects are off-plan with handovers between 2027 (Aria, October) and 2029 (Palm Jumeirah stock, December). Buying Beyond today means buying ahead of the brand’s first completion — which is where the entry pricing comes from.
Arancia Yards in City of Arabia, from around AED 1.0 million on a 10/30/60 plan. Within the flagship Dubai Maritime City district, Aria by Beyond opens at AED 1.6 million.
Mostly 10/40/50: 10% booking, 40% during construction, 50% at handover. The Palm Jumeirah projects use 10/50/40; Arancia Yards uses 10/30/60. Plan the 40–60% completion payment around the 50% off-plan mortgage cap.
It is an early-stage waterfront district: peninsula location minutes from DIFC, prices below established waterfront areas, and a masterplan still maturing. The trade is classic early-entry — upside if the district delivers on schedule, illiquidity and construction-phase inconvenience meanwhile. A 5+ year horizon is the sensible minimum.
For overseas investors (India, UK, US) with a growth mandate and cash to complete, the 2027-handover Maritime City towers offer a defined, short exposure window. It is unsuitable if you need rental income now, a visitable completed product, or a proven resale market. Consider pairing early-stage Dubai exposure with established Abu Dhabi stock.
Both are design-led; the difference is proof. Ellington has completed, inspectable buildings across Dubai since 2017 (scored 13/20 in our ranking); Beyond has a stronger parent and a better waterfront district but zero completions (11/20). Risk-averse design buyers start with Ellington; early-entry buyers with conviction in Maritime City look at Beyond.
Beyond is a bet with clearly defined terms: OMNIYAT’s design machine, a waterfront district being priced early, handovers from late 2027, and 50% handover balances. Our 11/20 score is not a warning — it is a measurement: unproven brand, strong parent, genuine opportunity. Buy it as an early-entry position sized to complete without leverage, and the risk profile makes sense.
How we verify this guide: Prices, payment plans and handover dates are indicative starting figures drawn from developer launch materials as at October 2026; group context references OMNIYAT’s public record and Dubai Land Department registration data. Verify live pricing, availability and registration before reserving.
Disclosure: Bramwell & Partners may act for buyers in some projects mentioned in this guide. Our analysis and scoring are independent of developers; no developer has reviewed or influenced this article.
Bramwell & Partners advises UAE residents and overseas investors across Dubai and Abu Dhabi. Enquire with our team for current Beyond availability, phase-level pricing, and an honest comparison against completed alternatives in both emirates.
Prices, plans and handover dates are starting figures correct at the time of writing; verify live terms before committing.
Institutional-Grade Investment Guidance
Talk directly to our advisory team
WhatsApp us at +971 56 494 7631 — we reply personally, usually within the hour.