Written by the Bramwell & Partners advisory team — Abu Dhabi real estate advisors. Last reviewed: October 2026.
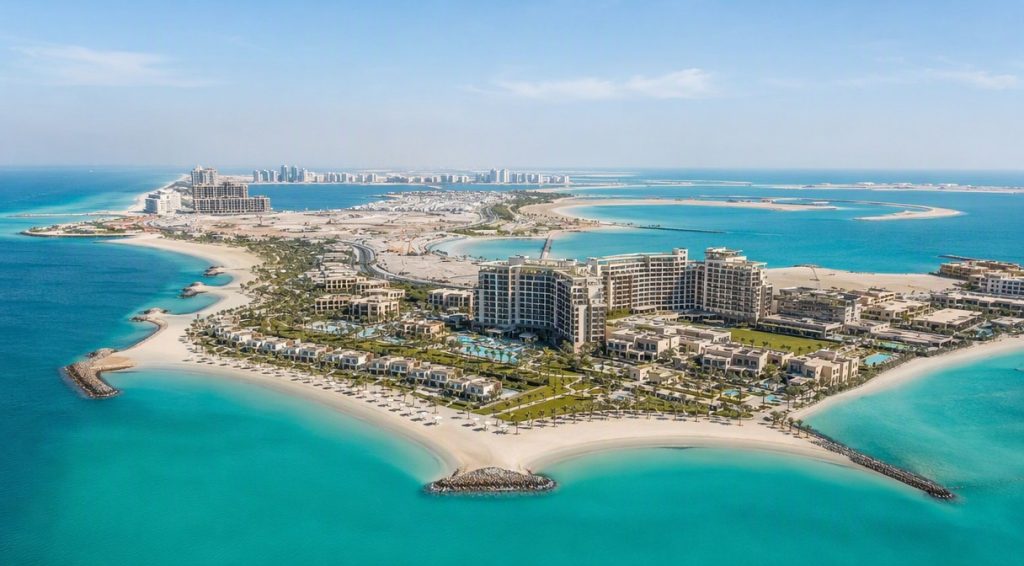
Wynn Al Marjan Island has crossed the line from construction story to opening story. The tower’s concrete structure topped out at 283 metres in December 2025 (its spire will take the final height to 352 metres), all 1,530 accommodation structures are complete, room fit-out is under way, and the resort’s own channels now consistently target a Spring 2027 opening. Restaurant leadership is hired, a 548-metre bridge to the mainland is being finished, a campus for 7,000 employees is being delivered, and an original Punchdrunk immersive theatre production — the company’s first in the Middle East — is booked for 2027.
For property investors, the construction milestones matter less than what they confirm: the $5.1bn resort, carrying the UAE’s first licensed land-based gaming facility, is arriving on schedule. This analysis looks past the cranes at what that means for Al Marjan Island real estate — with the honest caveats included.
Key takeaways
- Wynn Al Marjan Island is on track for a 2027 opening: all accommodation structures complete, 83% of facade panels installed as of February 2026, fit-out and commissioning under way.
- The resort brings 1,530 keys, 22 dining venues, 12 pools, a 420-metre beach, a theatre and a ~225,000 sq ft licensed gaming area — under federal GCGRA regulation.
- Ras Al Khaimah welcomed 1.35m overnight visitors in 2025 (+6%), with a government target above 3.5m by 2030; Wynn is the anchor of that trajectory.
- The investment case is strongest for well-located, well-managed apartments that work for owner-occupiers, long-let tenants and holiday guests — not for anything bought purely on "casino proximity".
- Risks are real: heavy new supply on Al Marjan, single-anchor dependence, and pricing that already capitalises much of the opening story.
| Element | Position (mid/late 2026) |
|---|---|
| Total project value | $5.1bn |
| Opening target | Spring 2027 (official recruitment/infrastructure updates) |
| Tower | Concrete topped out at 283m / 70 floors; 352m final height with crown and spire |
| Facade | 21,852 of 26,471 panels installed (83%) as of 2 Feb 2026 |
| Accommodation | 1,530 keys: 1,217 resort rooms, 297 Enclave suites, 2 Royal Apartments, 4 Garden Townhomes, 10 Marina Estates |
| Resort programme | 22 restaurants/bars/lounges, beach club, 12 pools, spa, 420m beach, retail promenade, marina, theatre |
| Events venue | Coral Court, 7,708 sqm incl. a 2,633 sqm ballroom |
| Gaming | Licensed land-based facility (~225,000 sq ft) under GCGRA regulation |
| Access | 548m Wynn Bridge (48% complete Feb 2026, due late 2026) linking to E311/E611 |
| Workforce | 7,000-person employee campus near RAK Central, due 2026 |
| Capital | Wynn holds 40% of the JV; $1.01bn cash contributed to date; $2.4bn construction facility completed Feb 2025 |
A brief construction pause during the March 2026 regional conflict was followed by resumed work, and Wynn’s May 2026 results continued to guide to a 2027 opening.
The most instructive precedent is Singapore. When Marina Bay Sands opened in 2010, it did not merely add hotel rooms; it converted its district into a global leisure landmark, pulled new visitor segments into the city, and anchored a decade of premium pricing in surrounding residential and commercial stock. The mechanism is repeatable: a regulated, landmark gaming resort creates a year-round demand generator (guests, diners, event delegates, theatre audiences, employees) that ordinary beachfront developments cannot manufacture.
Wynn Al Marjan has the same ingredients, at UAE scale: the country’s only licensed gaming operation, a federally regulated framework via the GCGRA, a convention venue sized for regional events, and a dining and entertainment programme designed to draw non-guests onto the island. Add the employee campus — 7,000 people needing housing, transport and services year-round — and the resort’s economic footprint extends well beyond its podium.
Ras Al Khaimah’s tourism base gives the resort something to accelerate rather than create from zero: 1.35m overnight visitors in 2025 (up 6% year on year), tourism revenue up 12%, and a stated target above 3.5m annual visitors by 2030, supported by expanding air links and hotel capacity.
Al Marjan Island’s residential market has been re-rating since the Wynn announcement, and most launches now price in a meaningful "Wynn premium". That changes how investors should buy:
Buy the property, not the postcode. Two apartments on the same island will perform differently based on distance from the resort, view permanence, beach access, layout, service charges and the operator’s rental programme. The coming years will reward assets that serve multiple demand types — an owner-occupier in winter, a long-let professional tenant, or a holiday guest during events — because flexibility is what survives changing market phases.
Short-let economics deserve real modelling. A resort-driven events calendar (conferences, theatre, dining weekends) supports nightly rates outside the traditional winter peak — but holiday-let returns must be modelled net of operator fees, furnishing, licensing and service charges, and stress-tested against the large volume of apartment supply completing on the island between now and 2028.
Watch the public realm as closely as the resort. Roads, promenades, beaches and completed neighbouring plots decide how the island feels on an ordinary Tuesday — which is what long-term tenants and future buyers ultimately pay for. The bridge, boulevard and employee campus completing through 2026 are therefore investment-relevant milestones, not just construction trivia.
Not all Al Marjan exposure is equal. Based on how landmark-resort markets have behaved elsewhere, we would rank the opportunity as follows:
The common thread is management quality. In a resort market, the operator running your building — housekeeping standards, booking channels, maintenance response — matters as much as the floor plan. Weigh the rental programme’s fee structure and track record as heavily as the purchase price.
Bramwell & Partners — Investor Proof
We help investors make money investing in Abu Dhabi properties — and we can prove it.
Download our Proof of Concept: three executed off-plan flips, real contracts, ≈62% blended ROI in 12 months with only 20% capital deployed.
Expert view from Bramwell & Partners
"Clients ask whether they should redirect Abu Dhabi allocations into Al Marjan. Our answer is that these are complementary, not competing, exposures. Abu Dhabi’s islands — Yas, Saadiyat, Hudayriyat — offer end-user depth and government-masterplanned scarcity. Al Marjan offers a tourism-and-gaming growth option with higher volatility and heavier supply. For diversified UAE portfolios, a measured RAK position alongside core Abu Dhabi holdings is defensible; an all-in bet on one island and one resort is not how we advise anyone to hold property."
In our advisory work, the question arrives in a consistent form: "Should I buy on Al Marjan before Wynn opens?" A representative brief, anonymised: an Abu Dhabi-based investor holding a completed Reem apartment asked whether to sell and redeploy everything into an Al Marjan launch. Our analysis showed the two assets doing different jobs — the Reem unit producing steady end-user rent today, the Al Marjan unit offering a tourism-growth option that pays nothing until handover and then depends on operator quality. The client kept the Reem income and added a measured Al Marjan position, sized so that a soft first year of island rents would not force a sale. That sequencing — core income first, growth option second — is how we would frame RAK exposure for most portfolios. For the emirate-level trade-offs, see our Abu Dhabi vs Dubai off-plan comparison.
Official recruitment and infrastructure updates target Spring 2027; the resort website states 2027 more broadly. An exact public opening date has not been announced.
A $5.1bn development with 1,530 accommodations (1,217 resort rooms plus 313 Enclave suites and residences), a tower reaching 352 metres, 22 dining and lounge venues, 12 pools, a 420-metre beach, a 7,708 sqm events venue and a marina.
It will contain the UAE’s first licensed land-based gaming facility — approximately 225,000 sq ft — with the operator listed in the federal GCGRA’s public licensee register.
The destination fundamentals are strong, but launch pricing already reflects much of the story. The case is best for high-quality, well-managed units that serve owner-occupiers, long-let tenants and holiday guests alike, bought at disciplined prices with a 5+ year horizon.
RAK offers a tourism-led growth story anchored by Wynn; Abu Dhabi offers deeper end-user demand, government-backed master developers and constrained island supply. Many investors hold both; the right weighting depends on your horizon and risk tolerance.
Multi-thousand-room resorts frequently adjust opening quarters during fit-out and commissioning. Current guidance remains 2027, but prudent investors model a 6–12 month slip without it breaking their thesis.
Wynn Al Marjan Island is no longer a promise; it is a fit-out schedule, a hiring plan and a bridge nearly built. Ras Al Khaimah is about to receive a demand generator no other UAE emirate currently matches. The investors who do best from it will be those who bought specific, well-run properties at sensible prices — not those who bought the headline.
How we verify this analysis
Construction and capital figures come from Wynn Resorts’ own updates, results and filings (February–May 2026), the GCGRA public register, Marjan’s project updates and RAKTDA’s 2025 tourism performance, each attributed with its as-of date in the text. Opening dates are operator targets, not guarantees, and forward-looking figures should be verified against the latest official updates before any purchase decision.
Disclosure: Bramwell & Partners may act for buyers in some projects mentioned; our analysis is independent of developers and operators, and we do not accept payment for coverage.
Weighing Al Marjan against Abu Dhabi’s island markets? Bramwell & Partners advises across the UAE’s coastal investment destinations from our Abu Dhabi base. We will model net yields, supply exposure and exit routes for any unit on your shortlist. Explore our off-plan projects and properties for sale and rent, or contact our advisory team for a private consultation.
Sources: Wynn Resorts construction updates, Q1 2026 results and 2025 annual filing; Wynn Al Marjan Island official communications; GCGRA public register; Marjan project updates; RAKTDA 2025 tourism performance. Figures as reported by those sources; forward dates are targets, not guarantees.
Institutional-Grade Investment Guidance
Talk directly to our advisory team
WhatsApp us at +971 56 494 7631 — we reply personally, usually within the hour.